The British Pound has demonstrated notable resilience in the early European session, trading with only mild losses around 1.3240 against the US Dollar. This stability comes at a time of significant global market turbulence, driven by a deepening sell-off in bond markets and heightened fears that the United States economy may be running too hot. While the broader financial landscape is defined by aggressive rate hike expectations in Washington, sterling has managed to hold its structural gains, suggesting that domestic economic data continue to support the currency's strength relative to its peers. The divergence between sterling’s performance and the broader risk-off sentiment highlights the specific drivers influencing the UK currency in the current macroeconomic environment.
Global Tightening Pressures
Financial markets have become increasingly confident that the US Federal Reserve will raise interest rates at least one more time this year. According to data from the CME Fedwatch tool, there is now a 55% chance that US rates will increase by another half a percentage point. This shift in market pricing has fueled a renewed surge in US Treasury yields, which are now exerting dual pressure on equity prices and bond values. The hawkish stance of the Federal Reserve has reinforced the strength of the US Dollar, creating a headwind for most other major currencies. However, the United Kingdom appears to be navigating these global tightening pressures with a degree of stability that contrasts with the volatility seen in other regions, particularly in Asia where stock markets have traded mixed ahead of key diplomatic meetings.
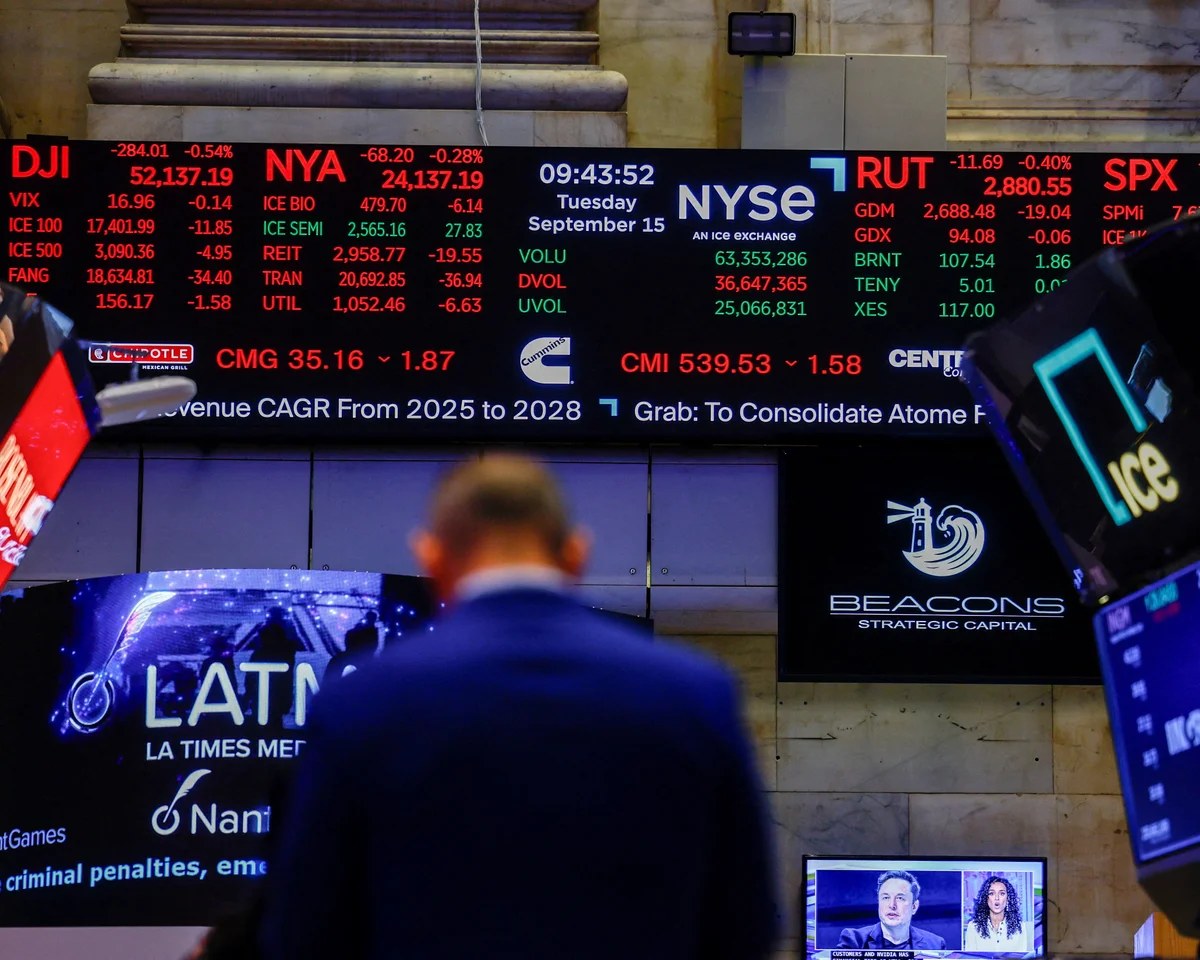
The global bond sell-off is not limited to the US, with Japanese 10-year bond yields soaring to a 30-year high amid bets on further rate hikes from the Bank of Japan. This parallel in major central bank signaling underscores a broader global trend toward monetary tightening. For UK investors and households, the implication is a more complex interest rate outlook. While the Bank of England’s path is influenced by domestic inflation data, the external pressure from hawkish central banks in the US and Japan adds a layer of complexity to sterling trading. Traders are positioning themselves carefully, balancing the local growth outlook against the global cost-of-carry implications that arise from rising yields abroad.
Domestic Inflation and Policy Signaling
Domestically, the narrative remains anchored on the fight against entrenched inflation. European Central Bank Governing Council member Martin Kocher stated on Thursday that the central bank must prevent too-high inflation from becoming entrenched, a sentiment that resonates with the broader G7 policy consensus. In the UK, the Bank of England faces a similar challenge, where the persistence of price pressures dictates the pace of monetary tightening. The sterling’s ability to hold gains despite the stronger US PMI data and hawkish Fed stance suggests that markets view the UK’s inflation trajectory as partially insulated from the most acute global shocks, or that domestic growth fundamentals remain robust enough to support higher real rates.
The current positioning reflects a cautious optimism among traders regarding the UK economy’s potential to withstand global headwinds. While the US Dollar benefits from the premium placed on higher yields, sterling is supported by its own domestic rate expectations. The fact that GBP/USD has not seen a sharp devaluation despite the global bond rout indicates that investors are not pricing in a significant divergence in growth prospects between the US and the UK. Instead, the currency pair is trading in a tight range, with support levels holding firm as long as domestic inflation signals do not suddenly deteriorate or improve in a way that would drastically alter the Bank of England’s policy path.
For UK households, this stability in sterling’s value offers some relief against the backdrop of rising global borrowing costs. The maintenance of the pound’s purchasing power, even in the face of a stronger US Dollar, is a positive development for those with international exposure. However, the underlying tension between global tightening and domestic economic resilience remains a key factor for market participants. As the year progresses, the focus will likely remain on the ability of central banks to manage inflation without stifling growth, with sterling’s performance serving as a barometer for the UK’s economic health in an increasingly volatile global market.